


Run an ASIC company search first to confirm the entity and its status, then order a commercial credit report from a bureau such as CreditorWatch, Experian Australia and Equifax. The bureau report gives you adverse listings, payment behaviour and director data. Cross-check against a PPSR search and ABN Lookup before you set terms.
Business Credit Check Australia: What a Credit Report Tells You Before You Extend Terms

Written by James Woods, Managing Director


Written by James Woods, Managing Director


At a glance
What a business credit report shows
Free checks before ordering a report
Red flags and what they mean
Setting credit limits and payment terms
Using deposits, guarantees and PPSR
What to do if a debt becomes overdue
Table of Contents
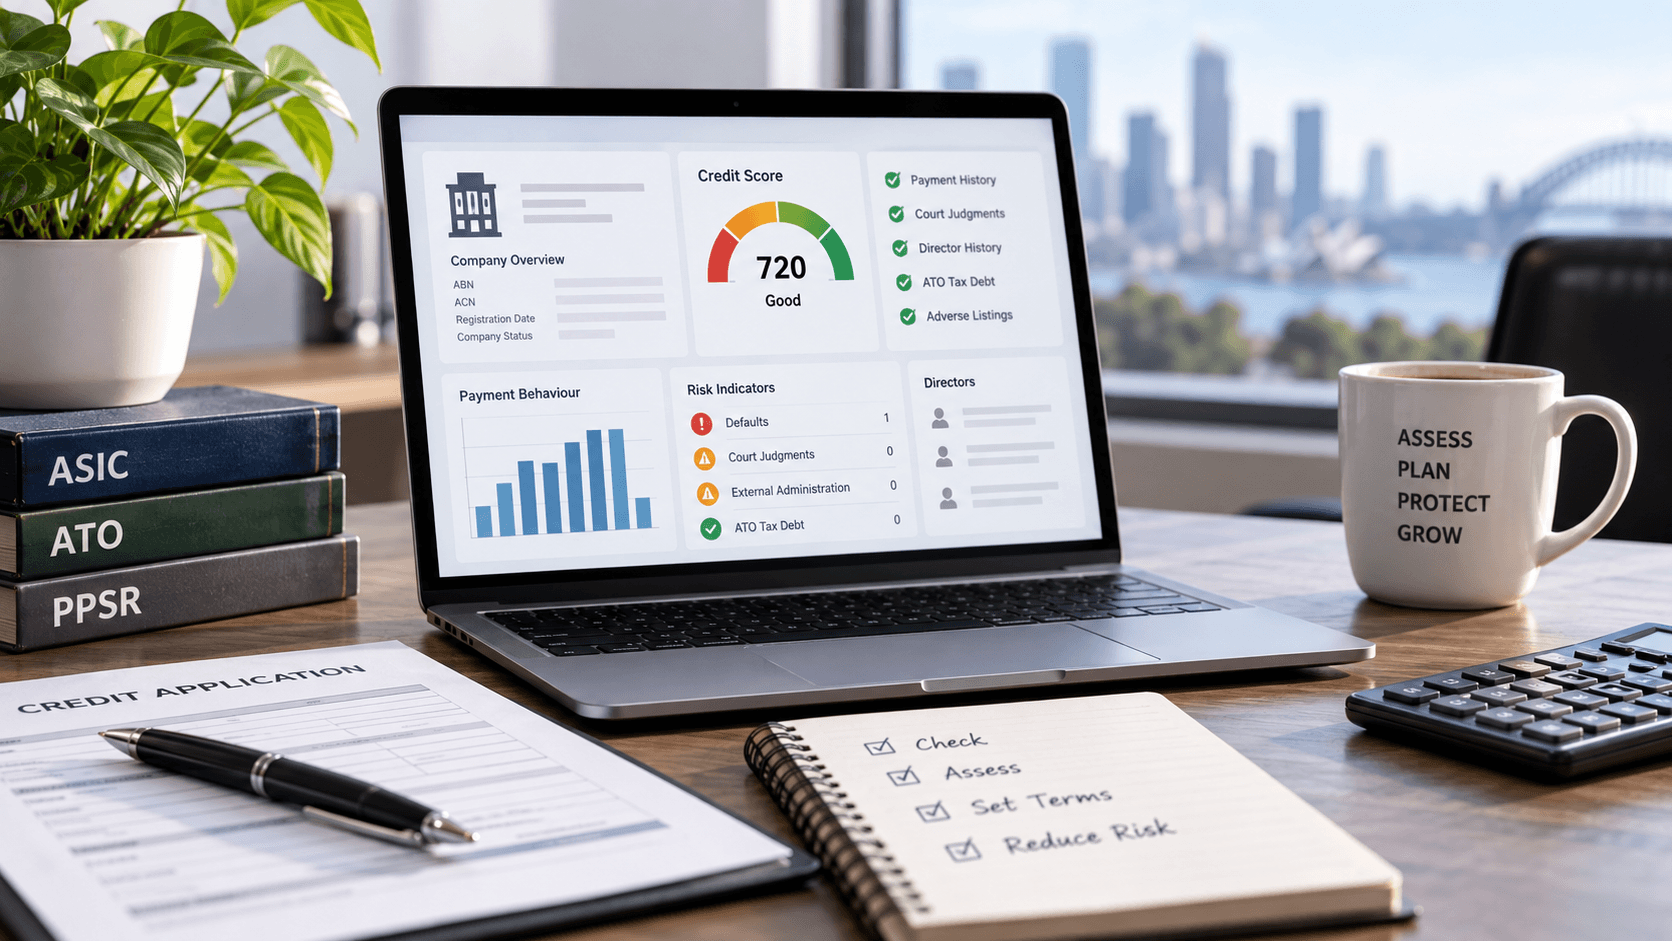
A business credit check is a search of a company's payment history, public filings and adverse listings, run before you hand that company an invoice they pay later. It tells you whether the business has defaulted before, whether there are court judgments against it, whether ASIC lists it as under external administration, whether the ATO has disclosed a tax debt, and how it's been paying other suppliers.
Reading the report is the easy part. Deciding the credit limit, deposit, guarantee or security you attach to the account is the part that actually protects the invoice.
This is general information and not legal advice. If you're drafting terms or chasing a specific debt, get advice on your situation.
What Shows Up on an Australian Business Credit Report
A commercial credit report pulls identity, structure and payment behaviour into one file. What you'll usually see:
Company identifiers: ABN, ACN, trading names, registration date and current status.
Directors and shareholders: named officeholders and any recent changes.
Adverse listings: defaults, court judgments and mercantile enquiries logged by other credit providers.
Payment behaviour: how the business has paid trade suppliers, often as a days-beyond-terms figure.
ATO tax debt disclosures: where the ATO has reported the debt to a bureau.
External administration flags: liquidation, voluntary administration, deregistration warnings.
Commercial credit information does not automatically follow the OAIC retention periods that apply to consumer credit reports. How long an adverse item remains visible can depend on the type of information, its original source and the bureau’s own retention practices. Check the notes in the report or confirm the period directly with the bureau.
The three main commercial bureaus in Australia are CreditorWatch, Experian Australia and Equifax. They draw on overlapping but not identical data sets, so a report from one won't always match a report from another. If you already understand how a default gets listed, you know what the adverse section of a report is showing you from the other side.
The Free Checks to Run Before You Pay for a Credit Report
Run the free searches first. They'll often tell you enough to price the risk on a smaller account without paying for a full bureau report.
ASIC company search. Free basic information includes ABN, ACN, ARBN or ARSN, registration date, next review date, registered-office suburb, state and postcode, and lodged documents. Paid extracts sit alongside: a current company extract is $10, current and historical is $20, roles and relationships is $23, and a certificate of registration is $23. Officeholder residential addresses aren't in the extract.
ABN Lookup. Confirms the trading entity, GST registration status and any historical name changes. If the name on the quote doesn't match the ABN, ask why before you invoice.
PPSR search. Shows whether security interests have been registered against the customer’s assets and which collateral they cover. It does not tell you how much remains owing or whether the assets are fully encumbered, so broad registrations should prompt further questions rather than an automatic conclusion.
Google and news search. Winding-up notices, ASIC insolvency notices, court listings and industry chatter often surface here first.
Two minutes on ASIC and ABN Lookup can flag the deregistered entity, the recently changed director, or the trading name that doesn't match the ABN on the quote.
Red Flags on a Business Credit Report and What They Mean
A single adverse entry may have a reasonable explanation. Several entries over a short period deserve more weight.
Default listings (a formal record that an account was overdue and unpaid). Commercial default-listing requirements are not the same as the OAIC rules for consumer credit defaults. Before listing an unpaid business account, check the bureau’s requirements, the terms accepted by the customer and whether the debt is genuinely disputed. A default from three years ago may be less concerning than three defaults recorded over the past two years.
Court judgments and repeated mercantile enquiries. A judgment means a court has entered judgment against the business. Check the case details to understand who brought the claim and what it involved. Multiple mercantile enquiries can indicate that collection agents have assessed or shown an interest in debts involving the business.
Recent director changes, deregistration warnings, external administration. A director resignation weeks before you extend terms is worth a phone call. External administration is a stop sign.
ATO tax debt disclosure. The ATO can disclose a business tax debt to a credit bureau where the business has an ABN, is not excluded, has one or more tax debts of at least $100,000 overdue by more than 90 days, isn't engaging with the ATO, and has no active IGTO complaint about the disclosure. If it appears on a report, treat it as a late-stage signal, not an early warning.
What to Do With the Report: Credit Limits, Deposits, Guarantees and PPSR
Use the findings in the report to set terms that reflect the customer’s risk.
PPSR registration. If you're supplying goods on retention of title, or leasing equipment, register on the PPSR. Timing matters. A security interest against a corporate grantor should be registered within 20 working days after signing the security agreement, or more than 6 months before insolvency. For PMSI super-priority, inventory must be registered before the grantor gets possession, and non-inventory PMSI within 15 working days. Registration outside these time limits may result in the loss of PMSI super-priority.
Personal guarantee from a director. A guarantee turns the director's personal position into a backstop. It only works if you actually run a director credit check before you accept it, and if the guarantee clause in the credit application is properly drafted.
Trade references, properly checked. Ring them. Ask what the credit limit is, what the terms are, and whether the account is current. If the referee cannot confirm those details, treat the reference as inconclusive.
If the safeguards fail and the customer still stops paying, here's what the recovery process looks like.
What a Solid Credit Application Form Should Capture
A useful credit application gives you enough information to assess the customer and pursue the account if it goes unpaid. At a minimum, it should capture:
Correct legal entity name, ABN and ACN, and trading names.
Registered office and principal place of business.
Named directors, with dates of birth for a director credit check.
Two trade references and the customer's bank details.
Written consent to obtain a credit report and to list a default if the account goes unpaid.
Personal guarantee clause, signed and dated by each guarantor.
Retention of title and PPSR consent where you supply goods.
Agreed credit limit, payment terms and a clear statement of interest and recovery costs on overdue accounts.
The consent language matters. Our legal and compliance framing covers the disclosure side. Get the form itself reviewed by a lawyer before you roll it out. This is general information, not legal advice for drafting.
If the Report Is Bad, or the Debt Is Already Overdue
A bad report isn't automatically a lost sale. Your options, in order of caution: reduce the credit limit, shorten terms, require a deposit, move to cash on delivery, or decline the account. Explain the decision in one line and move on. Businesses with clean books are used to being asked.
If you've already extended terms and the invoice is late, the sequence is straightforward. Start by calling the customer about the overdue invoice. If it remains unpaid, issue a formal letter of demand before deciding whether to place it with a collection agency. If the debt is disputed or the debtor ignores demands, court action becomes realistic. That's where an agency with an in-house law firm matters, because the file doesn't have to be handed to an external solicitor and re-briefed. E C Legal is eCollect's in-house team, which is why litigation on a placed file moves without the usual handover delay.
FAQs
A personal credit check reports on an individual's consumer credit history under the Privacy Act. A business credit check reports on a company or trading entity, drawing on ASIC data, court records, trade payment data and any ATO tax debt disclosures. If a director is giving a personal guarantee, you usually need both.
There is no single OAIC retention schedule covering every item on a commercial business credit report. The period can depend on the type of information, its source and the bureau holding it. Ask the bureau how long the specific entry will remain visible.
You generally do not need consent to obtain a commercial credit report on a company. If you want to access a director’s consumer credit report to assess them as a guarantor, you need their express consent. That is different from checking their publicly available directorship history through ASIC.
You may still decide that a guarantee is appropriate even when the report is good. Company scores reflect the past, and the entity behind the ABN can change quickly. For [small business](https://www.ecollect.com.au/small-business-debt-collection-agency) accounts especially, a director guarantee gives you a second recovery path if the company later fails.
Repayment history information (RHI) is the month-by-month record of whether you paid consumer credit accounts on time. It sits under comprehensive credit reporting and updates every month. A default is a separate, harder event that only lands after the 60-day, $150, two-notice sequence has been run.
Free ASIC search fields cover ABN, ACN, ARBN or ARSN, registration date, next review date, registered-office suburb, state and postcode, and lodged documents. Paid extracts add officeholder details, share structure and history: current extract $10, current and historical $20, roles and relationships $23, certificate of registration $23. Residential addresses of officeholders aren't included.
No. Use a PPSR search to see which security interests are already registered against the business’s assets. A credit check tells you the business's payment history and adverse listings. Run both. A clean credit file does not cancel out broad PPSR registrations, but the registrations alone will not tell you how much debt remains or what equity is available in the assets.
If You Are Already Chasing an Overdue Invoice
Prevention is cheaper than recovery, which is the whole point of running the check before the invoice goes out. If you're past that point and the account is already overdue, the next step is a straight commercial assessment of the debt. Send it through the free debt appraisal and we'll tell you what's worth pursuing and how. This page is general information and not legal advice.
References
James Woods
Managing Director
James has operated businesses since his late teens including windsurfer hire (1977 – 1981), yacht charter (1990 – 2001), motor accident repairs (1984 – 1989) and debt recovery (2002 to the present). He holds a B.A. and LL.B. from Monash University and was admitted as a lawyer in 1983. He is also a Graduate of the Australian Institute of Company Directors.


Let’s recover your debts without the stress
We make debt recovery simple, fast, and results-driven. Upload your files, track progress in real-time, and only pay when we collect.
Let’s recover your debts without the stress
We make debt recovery simple, fast, and results-driven. Upload your files, track progress in real-time, and only pay when we collect.


Together, we deliver complete debt solutions
From proactive receivables management through to complex legal recoveries, the eCollect Group provides an integrated, transparent, and results-driven solution — powered by technology, guided by expertise, and delivered by people who treat your business like their own.
Trusted in Australia, New Zealand & Beyond
Melbourne
03 8611 2600
Level 9, 461 Bourke Street, Melbourne VIC 3000
Sydney
02 9191 9699
Level 6, 115 Pitt Street Sydney NSW 2000
Brisbane
07 3123 4031
Level 38/71 Eagle Street Brisbane QLD 4000
Auckland
+64 9 951 8000
Spaces, level 7, 50 Albert St, Auckland CBD, Auckland 1010 NEW ZEALAND
UK - eRecoveries
erecoveries.co.ukOur eRecoveries service based in UK applying high-end technology to cover the full receivables management process for you


eCollect
Our core debt recovery and collection service, operating across Melbourne, Sydney, Brisbane, and Auckland.
E C Legal
Specialist legal support for debt and credit matters, based in Australia.
eclegal.com.aueReceivables
Designed for Australian receivables management and credit operations, uniting intelligent software with real operational expertise.
ereceivables.com.aueRecoveries
Expanding our debt recovery expertise across the United Kingdom market, supported by advanced systems, industry trained specialists and a proven no-recovery, no-charge model.
erecoveries.co.uk